For roofers, plumbers, restoration and repair contractors
The claim got denied. The job doesn't have to die.
When an insurer denies or underpays your customer's claim, SureClaim's licensed public adjusters take it up for the homeowner at no upfront cost. When it's paid, the repair goes ahead, and you're the contractor they already chose.
Houston metro · Attorney-led public adjusters · No fee to the contractor
Become a SureClaim partner
Takes about a minute. Then pick a time for a 10-minute meeting by Zoom, phone or in person.
You find the damage. We handle the claim. You do the repair.
Contractors in Texas can't negotiate a claim for a homeowner. Licensed public adjusters can. That's the whole arrangement.
Send the homeowner our way
A customer with a denied, delayed or lowballed claim. With the homeowner's OK, introduce us. It takes two minutes.
We work the claim
We inspect, document the damage and build the claim's supporting evidence, write the line-item estimate and deal with the carrier. If the claim needs legal advice, we'll explain the next step.
The repair gets funded
When the claim is paid, the homeowner has the money to do the work properly, and you build a job that's already approved.
Plumbers & water restoration
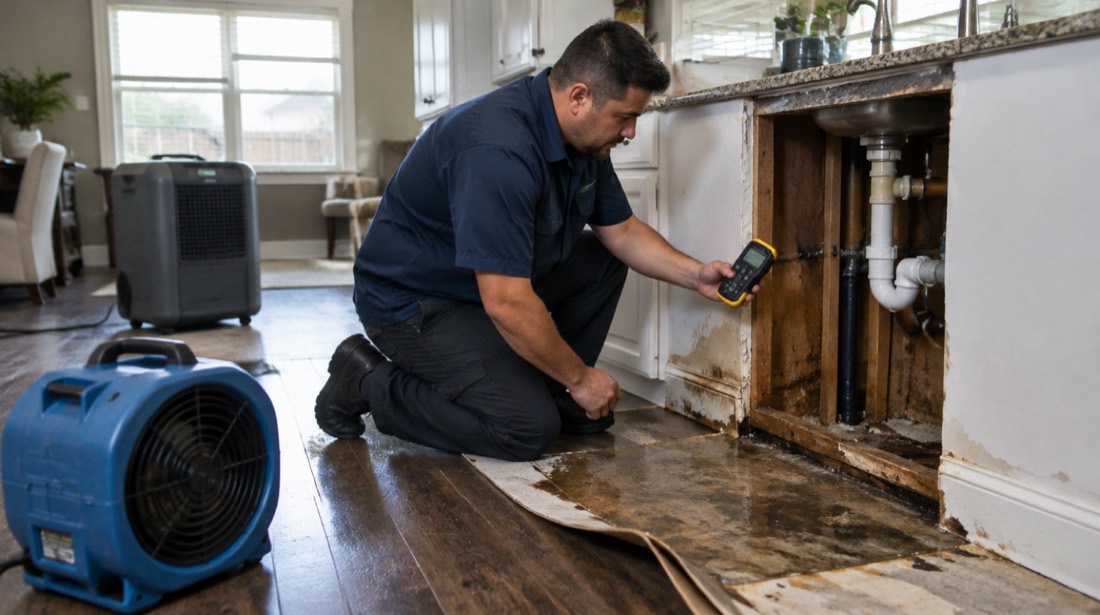
You stopped the leak. Then the insurer said “long-term seepage.”
You're the first one in the house, usually before a claim is even filed. What happens to that claim decides whether the tear-out, dry-out and rebuild ever get paid for.
“Long-term leak” denials
The carrier calls a sudden pipe failure a slow drip and denies the whole claim. The homeowner can't afford the repair, so the bigger job never happens.
Dry-out invoices cut after the work is done
A bill reviewer trims your equipment days and line items weeks later, and you're left chasing the balance.
The homeowner gets steered to the insurer's vendor
You found the loss and did the emergency work. The rebuild goes to a preferred contractor you've never heard of.
“Is this covered?”
When the homeowner asks about coverage, give them a claim professional to call.
Covered tear-out nobody claims
Depending on the policy and cause of loss, coverage may include opening the slab or wall to reach a failed pipe, even when the pipe itself isn't covered. Homeowners rarely know to ask.
Mold limits and water sublimits
Policy limits can change what the claim pays. Review them early.
What we do about it
- Bring us in earlyWhile the damage is still wet and before anything is torn out undocumented.
- Policy and evidence togetherWe review the policy alongside the damage documentation. Emergency mitigation should continue.
- The whole loss is documentedEmergency service, dry-out, tear-out and rebuild are documented and presented together.
- We contest “seepage” denialsWe compare the denial with the policy and the documented cause and timing.
Keep emergency work moving. Document conditions safely as you go; don't wait for a claim review to stop water or prevent further damage.
What's in it for your business
- Dead jobs come backThe estimates you wrote off when the carrier said no.
- Less claim babysittingWe handle the carrier, the supplements and the appeals. You stay on the roof.
- Free drone roof scans and hail historyAddress-level storm reports you can use on your own inspections.
- Clear rolesYou handle the repair. We handle the homeowner's claim.
The straight answer on money
No referral payments. No fee to the contractor.
The homeowner pays nothing upfront. The homeowner's fee is explained before they hire us.
What you get is the job, funded.
Questions contractors ask
Does this cost me anything?
No. There's no fee to the contractor. The homeowner pays nothing upfront, and the homeowner's fee is explained before they hire us.
Do you pay referral fees?
No referral payments. No fee to the contractor. The benefit to you is a claim that gets worked properly and a repair that can go ahead.
Will you send my customer to another contractor?
The homeowner chooses their contractor. If they came to us through you, they already have.
What kinds of claims?
Hail, wind, water, fire and mold claims on homes across the Houston metro area, including claims that were already denied or paid short.
What happens after I sign up?
You can pick a time for a 10-minute meeting by Zoom, phone or in person right away, or we'll contact you to set one. We'll walk you through how introductions work.
Which job came to mind?
Tell Cedrick which kind of claim is holding up the work.